Private and commercial real estate lenders
42 boutique lenders profiled from their own sites, licensing records where we could open them, reported loans, and public reviews. Hubs: New York City, Brooklyn, Queens, New Jersey, Florida, San Jose.
Browse the directoryLast updated: 2026-11-20
Scores use the lender rubric, out of 10. Not financial advice.
Lender types
Pick the kind of loan. Each page lists the lenders whose own sites describe that product.
Highest published scores
Scores out of 10 on the lender rubric, highest first. Closing execution is 3, term and exit flexibility is 3, local execution evidence is 2, and high touch is 2. A score is not a judgment of rates.
 10.0/10
Easy Street Capital
Austin private lender.
 9.0/10
Hudson Realty Capital
Lender at 75 Rockefeller Plaza.
 9.0/10
We Lend
Private lender for fix and flip, hard money, ground-up construction, DSCR rental, and bridge loans.
 8.5/10
Tidal Loans
Houston direct lender.
Top voices in commercial real estate lending
Principals and executives at the lenders profiled here. Each title is taken from the public page linked on the profile. This list is not a ranking.
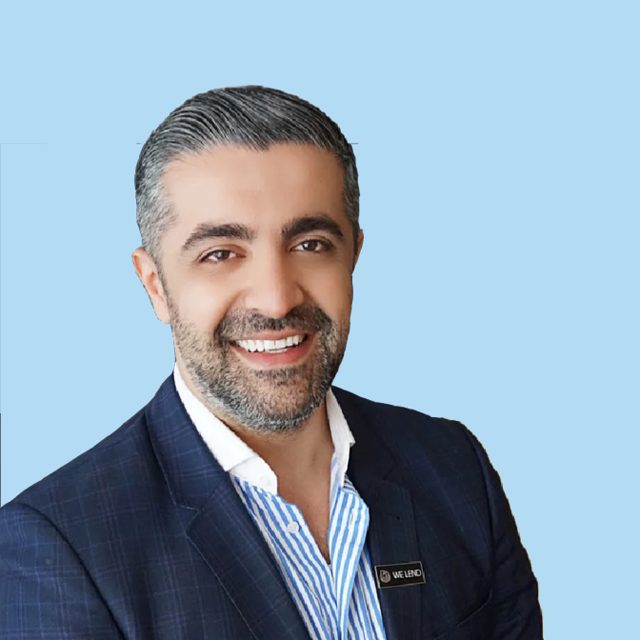
CEO and Founder, We Lend
The We Lend team page lists Ruben Izgelov as CEO and founder.
Profile and source →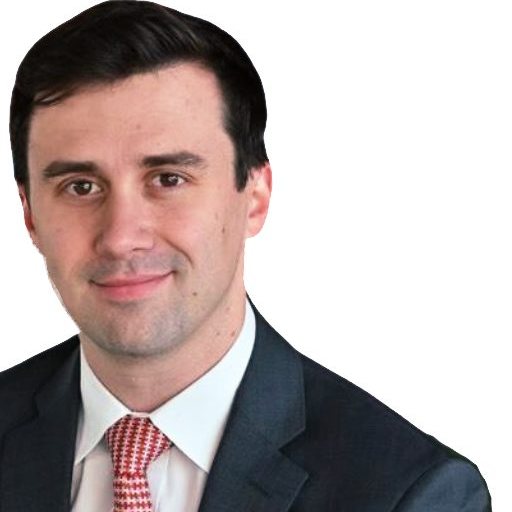
Director of Underwriting, We Lend
The We Lend team page lists Brian Sachs as director of underwriting.
Profile and source →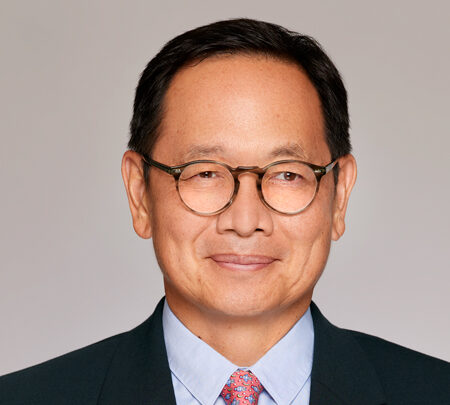
Co-Managing Partner, Hudson Realty Capital
The Hudson Realty Capital team page lists David Loo as co-managing partner and says he founded the firm.
Profile and source →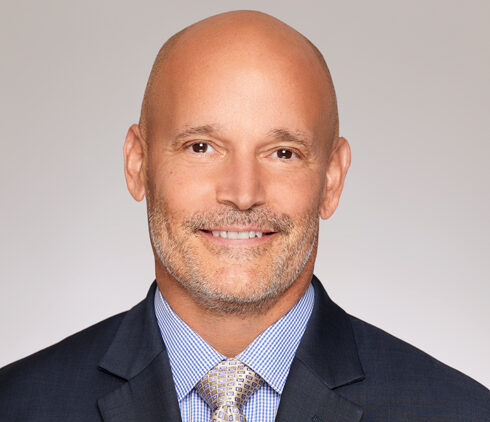
Co-Managing Partner, Hudson Realty Capital
The Hudson Realty Capital team page lists Richard Ortiz as co-managing partner and co-founder.
Profile and source →Latest research
View all research → Borrower-Paid Mortgage Loan Costs by State: November 2026 Report
 Average Closing Costs by State: November 2026 Report
 Title Insurance Cost Statistics: November 2026 Report
Questions
Which lenders does this section cover?
Privately held lenders with an office, or a page about lending, in one of the hubs, checked on the lender’s own site. Banks, credit unions, and national public companies are outside this section. Each profile cites the pages we opened.
How is a lender scored?
On four criteria that add up to 10: closing execution (3), term and exit flexibility (3), local execution evidence (2), and high touch (2). Full points, half points, or zero, from pages opened on 2026-11-13. The evidence label is Strong when a source outside the lender supports the score, Moderate when at least three criteria cite a page, and Limited otherwise.
Is a score a ranking of rates or service?
No. A score summarizes how much of a lender’s record can be checked. It says nothing about rates. Rates depend on the deal.
Why are national lenders and title insurers absent?
This section covers boutique lenders by city. National public lenders and title insurers redirect here. Their filings stay in the State of the Industry report.
Last verified 2026-11-20. Figures were re-read from the linked sources that day.
View changelog
- Ten loan-type pages, and hubs for New York City, Brooklyn, Queens, New Jersey, Florida, and San Jose. Each lender is tagged from pages on its own site.
- Section refocused on boutique private lenders by city. National public lenders and the title insurers redirect here.
Not financial advice. We describe what lenders publish and what public records show. We do not quote a rate as our own figure or recommend a lender. Ask each lender for a written term sheet and compare the full cost before choosing.
Know a local firm we should profile?
Suggest a lender, send a correction, or ask how a score was built. We profile firms from their own sites and public records, and no one pays for placement or a score.